Madison and Guilford Market Update: Rates Just Crossed 7%. Here's What It Changes for Sellers.
How is the Madison and Guilford, CT housing market doing heading into October 2026? Still strong: Madison's median sale price is up 13.1% and Guilford's up 9.6% year over year. But the 30-year rate hit 7.03% on Sept 24, so fall buyers are working with tighter monthly budgets than summer buyers had.
Two things are true about our market right now, and most of the coverage you'll see only tells you one of them.
The first is that the summer numbers in Madison and Guilford were excellent. Prices up, days on market down, a majority of homes in both towns selling over asking. If you read those headlines and thought, "good, I'll list in October and get the same result," I understand exactly why.
The second is that the buyer walking through your front door this October is not the buyer who set those numbers. That buyer is shopping with a mortgage rate that went from 6.76% to 7.03% in two weeks. Same house, same street, different math.
Here's what both sides look like, and what I'd do about it.
The summer numbers: still strong in both towns
These are Redfin's figures for the three months ending August 2026, the most recent reading available. The September reading will post in October.
Madison (06443)
Madison's market page shows a median sale price of $797,155, up 13.1% from the same period last year. Median days on market was 43, one day faster than a year ago. Sale-to-list came in at 102.4%, and 55.6% of Madison homes sold above list price, up 6.1 points.
Guilford (06437)
Guilford's market page shows a median sale price of $766,968, up 9.6%. Median days on market was 39, nine days faster than last year. Sale-to-list was 103.6%, and two out of three Guilford homes (66.7%) sold above list.
Side by side
That last row matters. Both towns sold fewer homes this August than last year while prices kept climbing. That's buyer demand vastly outpacing inventory, in plain numbers. It's also the reason I'm not telling anyone to panic about rates.
What changed in September
Here's the part the summer numbers can't show you.
According to Freddie Mac's weekly survey, the average 30-year fixed rate was:
→ 6.76% on September 10 → 6.95% on September 17 → 7.03% on September 24
A year ago this week it was 6.30%.
The homes in that Redfin data closed in June, July and August, which means most of those deals were negotiated in spring and early summer. Those numbers are a rear-view mirror. They tell you what the market was willing to pay, and they're a great starting point. They are not a promise about October.
What that looks like in a buyer's monthly payment
Buyers don't shop by price. They shop by payment. So let's run it.
Take an $800,000 home, right around the median in both towns, with 20% down. That's a $640,000 loan on a 30-year fixed. Principal and interest only:
That's roughly $116 more a month than two weeks ago and about $309 more a month than last fall, for the exact same house.
Flip it around and it gets more interesting. A buyer who was comfortable at the $4,155 payment on Sept 10 can now borrow about $623,000 instead of $640,000 for that same payment. At 20% down, that's roughly $778,000 of house instead of $800,000.
Nobody's buyer pool just vanished. But some buyers who were looking at $800,000 on Labor Day are now filtering their search at $775,000 or $780,000, and if your home sits right on the line, that's the part worth paying attention to.
(These are illustrations using a simple loan calculation, not a quote. Taxes, insurance and every buyer's actual loan terms will vary.)
What it doesn't mean
It doesn't mean prices in Madison or Guilford are about to drop. Our towns have been tight on inventory for a long time, and one rate move doesn't manufacture more houses. Sixty-seven percent of Guilford homes going over asking doesn't unwind in three weeks.
It also doesn't mean you should wait. Nobody knows where rates go next, including me. What I do know is that every fall the buyers who are still out after Labor Day tend to be serious ones, with a reason to move before the holidays or the new year.
What it does mean is that the margin for a mispriced home just got thinner. In the summer, a home that came out a little high could get rescued by a crowd of buyers. In October, with fewer buyers and each one watching the payment more carefully, the same home is more likely to sit and then cut.
What I'd do if you're selling in Madison or Guilford this fall
→ Price to October, not to August. Use the summer comps as your foundation, then think about where today's buyer is actually searching. If you're choosing between $799,000 and $815,000, that $16,000 may decide whether you show up in a buyer's search at all.
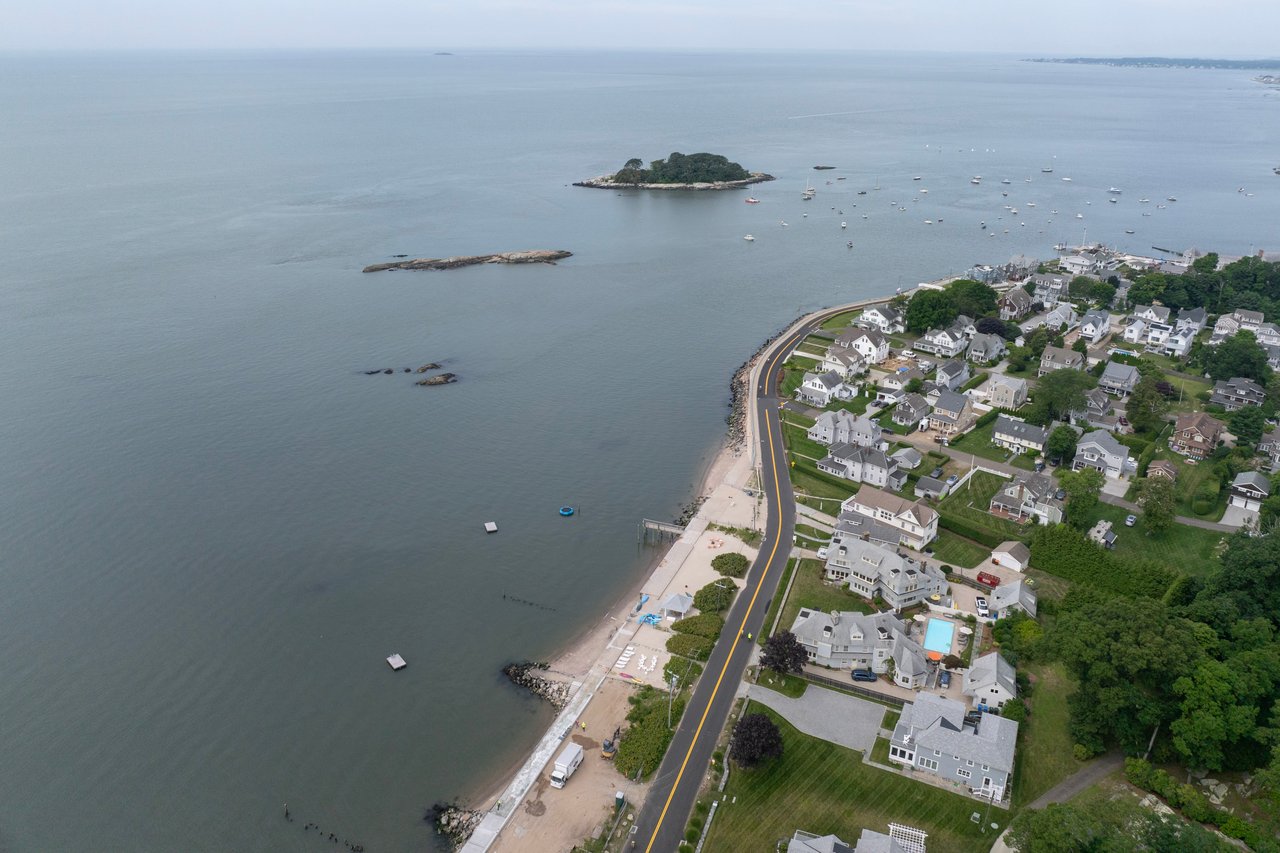
→ Think about your location's buyer. Madison isn't one market. The buyer looking up near Rockland Preserve is weighing space and trails, and the buyer who wants to be close to Salt Meadow Park or the Madison Surf Club is paying for being near the water. Guilford splits the same way, from North Guilford out past Lakeside Farm Stand to the streets closest to the Sound. Each of those buyers reacts to a rate move differently, and your pricing should reflect who's actually coming to see your home.
→ Put a rate-buydown credit on the table instead of a price cut. A seller credit that a buyer can use to buy down their interest rate often does more for their monthly payment than the same dollars taken off the price. It's a real conversation to have with your attorney and the buyer's lender, and it's one of the most useful tools I have in a market like this one.
→ Be ready on day one. Prepped well, marketed aggressively, and priced right is still the playbook. In a rate-sensitive month, the first ten days of your listing carry even more weight, because that's when the most motivated buyers are paying attention.
→ Watch the October reading. When Redfin posts September data next month, we'll see the first real picture of how our two towns absorbed the move. I'll be reading it closely, and I'll share what I see.
FAQ
What is the median home price in Madison, CT right now? Over the three months ending August 2026, the median sale price in Madison 06443 was $797,155, up 13.1% from a year earlier, according to Redfin. About 55.6% of Madison homes sold above list price.
What is the median home price in Guilford, CT right now? Guilford 06437's median sale price was $766,968 over the three months ending August 2026, up 9.6% year over year. Homes went under contract faster than last year, with a median of 39 days on market, and 66.7% sold above list.
Do higher mortgage rates mean I should wait to sell my Madison or Guilford home? Not necessarily. Rates rose to 7.03% in late September, which trims some buyers' budgets, but inventory in both towns remains tight and prices are still up year over year. The bigger risk this fall is pricing to summer numbers instead of today's buyer.
Figures: Redfin's 06443 and 06437 market pages, three months ending August 2026; mortgage rates from the Freddie Mac Primary Mortgage Market Survey, week of September 24, 2026. Payment examples are illustrative principal-and-interest calculations only. Conditions vary street by street.
Call or text me at 203.687.6997. I'd love to talk through what your home could do in this market.
Jules G. Etes | Guilford | Madison Real Estate Strategist Top 1% Nationally | $283M+ Sold | MBA William Pitt Sotheby's International Realty "Opening the doors to your real estate dreams…"